ServicesHotshot Truck Insurance
Hotshot Truck Insurance in Palmetto
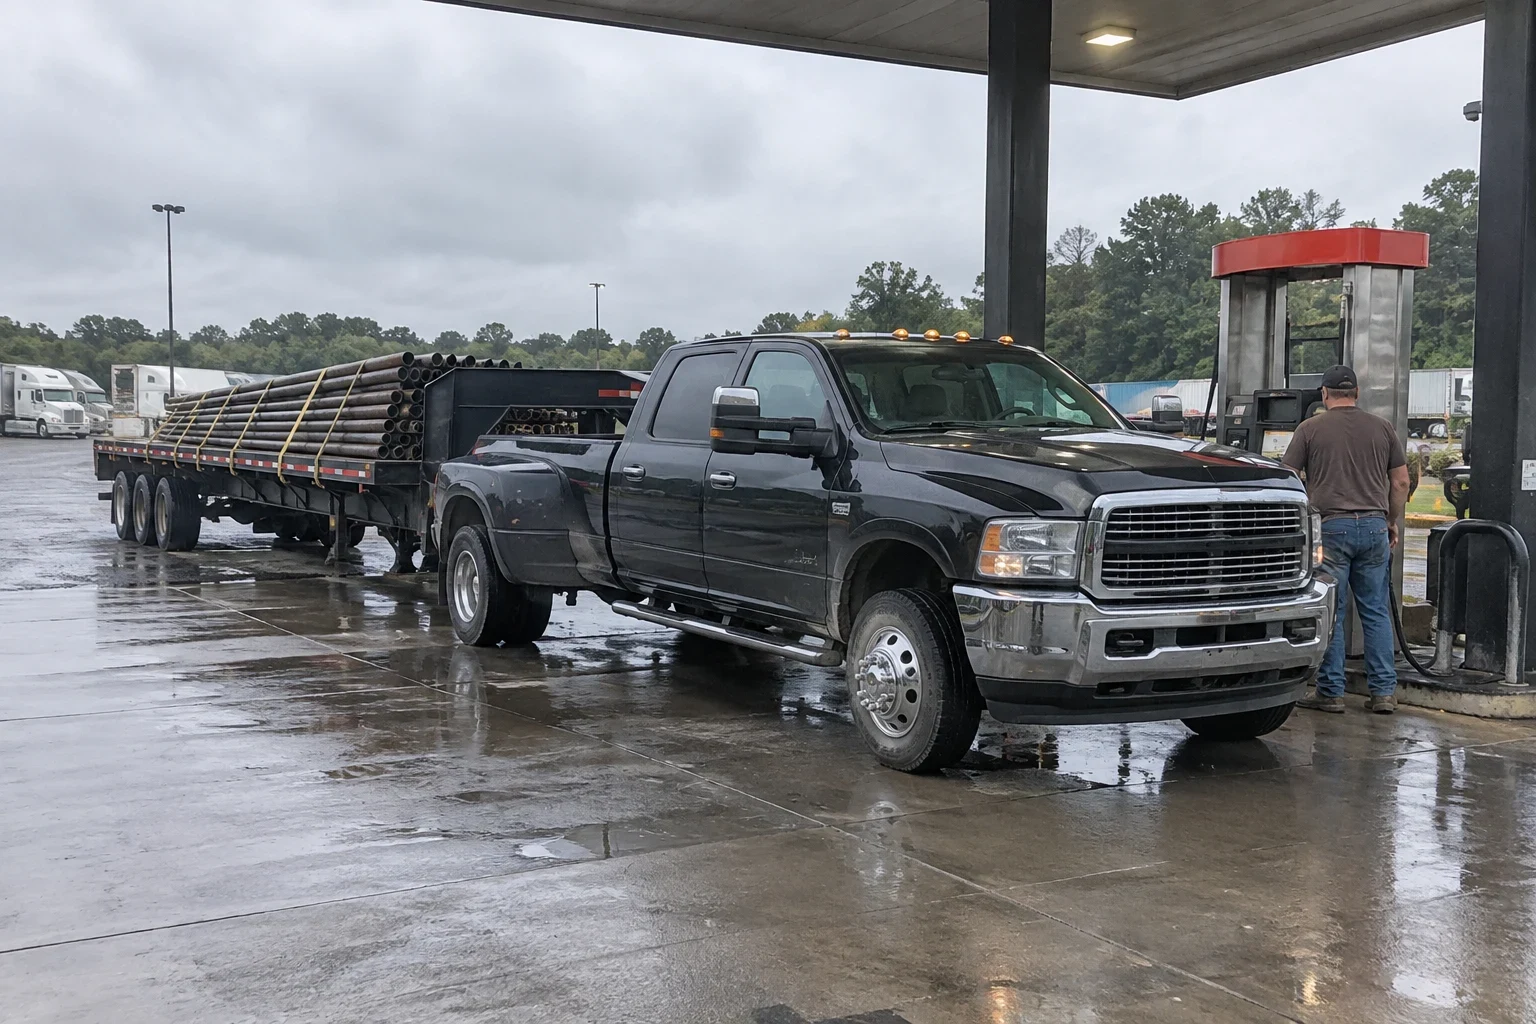
Hotshot work runs on a heavy pickup, a flatbed or gooseneck trailer and tight load-board deadlines. We put together hotshot truck insurance that covers the liability, the cargo and the equipment. Then we walk you through each piece in plain words so you know what you are paying for.
What hotshot coverage is and who needs it
Hotshot trucks are hard to classify at first glance. It looks like a pickup, but haul freight for money and it becomes a commercial vehicle. Personal auto coverage excludes for-hire hauling, so a wreck with a paying load can leave you with no claim paid. When the truck and trailer carry a combined rating over 10,001 pounds and you run across state lines, you need a DOT number. Interstate for-hire work also calls for MC authority and a liability filing with the FMCSA.
We hold a license for property and casualty insurance, and we have spent 5 years in business covering hotshot drivers in Palmetto, Fairburn, Union City, Newnan and nearby. A lot of what we do is explaining. You hear what every line of the quote means, what brokers will want to see, and where a lower price is hiding a hole in the coverage.
The pieces that make up hotshot coverage
- Primary auto liability
- If you hurt someone or damage their property on the road, this is the part that pays them. Your authority filing rests on it. Plenty of brokers want more than the federal minimum, so we confirm their limit before anything is bound.
- Motor truck cargo
- This covers the freight on your trailer when it gets damaged or goes missing. Hotshot freight tends to be machinery, steel, pipe or building materials. We go through the list of covered commodities and the exclusions with you, such as unattended truck or securement rules, so a load you pull every week is not left out.
- Physical damage for truck and trailer
- When your own equipment is wrecked, stolen, burned or hit by hail, this pays to fix or replace it. Each unit gets its own stated value. You choose the deductible, and we show how that choice moves the premium.
- Filings and certificates
- We take care of the BMC-91X liability filing your MC authority needs. When a broker or shipper asks for a certificate of insurance, we send it to them.
- If you are leased on
- Running under another carrier's authority means their liability covers you while dispatched. For the hours you are off dispatch, you may need Non-Trucking Liability (Bobtail) Insurance instead.
Signs it is time to look at your hotshot coverage
You are hauling paid loads on a personal policy
This is the most common gap we see. One claim on a paid load can be denied, and the policy can be cancelled.
A broker turned down your certificate
Usually the liability or cargo limit is too low, or the broker is not listed as a certificate holder. Both can be fixed.
Your loads outgrew your cargo limit
A skid steer or a stack of steel on a 40-foot gooseneck can be worth more than a small cargo limit. Check your load confirmations against your policy.
You added a trailer or a second truck
New equipment needs to be listed. An unlisted trailer may have no physical damage coverage at all.
You are getting your own authority
Moving off a lease means you carry your own liability and filings. Our New Authority Truck Insurance page covers that first year in more detail.
What pushes a hotshot premium up or down
Nobody sets one flat price for hotshot coverage. Each insurance company looks at your risk its own way, and a handful of things do most of the work. We point out which of them apply to your operation so the number on the quote makes sense.
Your driving history
Tickets, accidents and how long you have driven commercially count the most. A newer driver can still get covered, just with fewer companies willing to write it.
How old your authority is
A fresh MC number comes with no history for an underwriter to judge. As you stack up clean years, the premium usually comes down.
What your rig is worth
The cost of physical damage coverage follows the value you put on the truck and trailer. A late-model dually with a new gooseneck runs higher than older units.
Freight and miles
Hauling heavy equipment over long runs is seen as riskier than short regional trips with building materials.
Limits and deductibles you pick
Raising your liability or cargo limit raises the premium. Taking a bigger deductible brings it down, as long as you could pay that amount out of pocket after a loss.
How getting covered works
- 1
Start with a phone call
We ask about the truck, the trailer, the freight and the distances you run. If you have DOT and MC numbers we take those too, along with your driving record.
- 2
We check with the companies that write hotshot
Only some insurance companies take on hotshot work. We send your details to those and line up what they offer.
- 3
We walk the quote with you
Limits, deductibles and exclusions get explained in everyday words. When a cheaper option costs less because it covers less, we tell you that plainly.
- 4
Policy starts, paperwork goes out
After you choose, we put the policy in force, submit the filings tied to your authority and get certificates to the brokers you haul for.
- 5
Updates as you go
Picked up a trailer, sold a truck or signed with a new broker? Call us and we change the policy to match.
Hotshot insurance questions we hear
Can I use my personal pickup insurance for hotshot loads?
No. Personal auto policies exclude hauling for hire. If you have a wreck with a paid load, the claim can be denied and the policy cancelled. You need a commercial policy before the first load.
Do I need my own MC authority?
Not always. If you lease onto a carrier, you run under their authority and their liability. If you book your own loads across state lines, you need your own MC authority and your own liability filing. We can talk through which setup fits your operation.
How much cargo coverage do brokers want?
It depends on the broker and the freight. Many set a minimum in their carrier packet, and some loads require more. Check your load confirmations, then we match your cargo limit to what you actually haul.
Is my trailer covered when it is hooked to the truck?
Liability generally follows the trailer while it is attached. Damage to the trailer itself is a separate matter. It needs to be listed on your physical damage coverage with its own value.
Can you send certificates to my brokers?
Yes. Give us the broker's name and details and we send the certificate of insurance. We can add them as a certificate holder when they ask for it.
Talk through your hotshot setup
Tell us about your truck, your trailer and what you haul. We will explain your options in plain words and put a quote together.