ServicesDump Truck Insurance
Dump Truck and Construction Truck Insurance in Palmetto
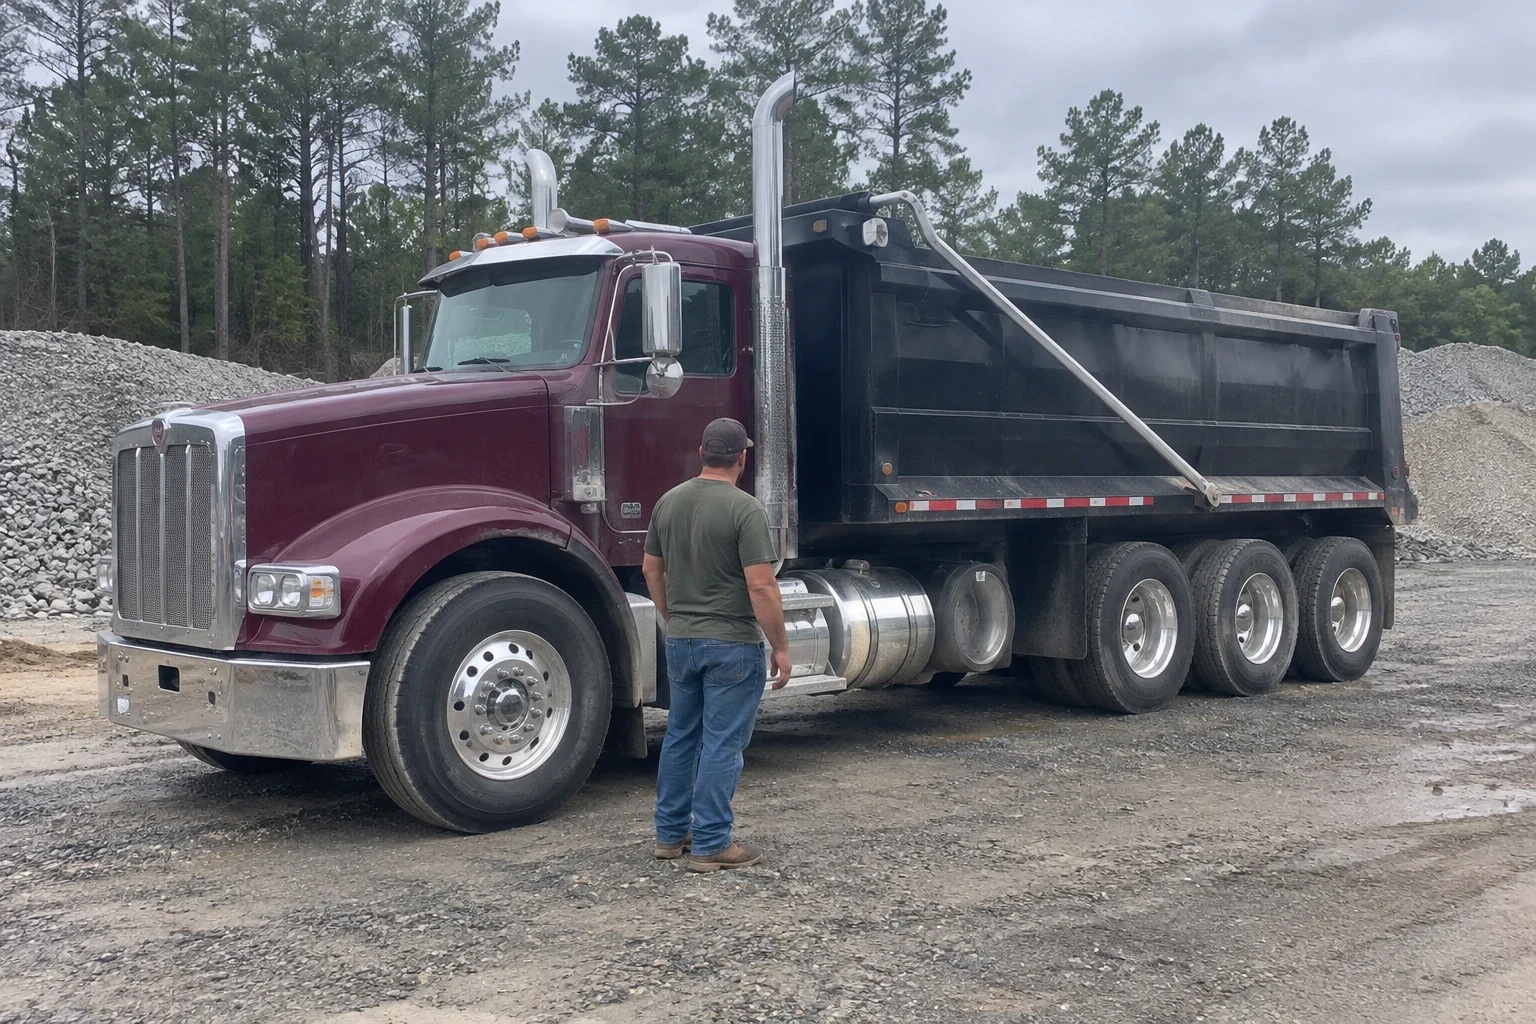
Dump trucks get rated differently than over-the-road rigs. Short hauls, heavy loads, job sites and contractors who want paperwork before you roll in. We put your coverage together piece by piece and tell you what each part does in plain words.
What this coverage is for
Dump truck and construction truck insurance is a group of policies built around how you actually run. Most operations need primary auto liability for damage you cause to others, physical damage for your own truck, and the right filings if your DOT number or MC authority calls for them. Some also need cargo coverage or non-trucking liability, depending on who you haul for.
The details matter more here than on most trucks. A tri-axle hauling gravel ten miles from the pit carries a different risk than a tandem moving fill between sites, and the policy should say so. We have been doing this for 5 years, and most problems we see come from a policy written for the wrong kind of hauling.
What we look at and set up
Primary auto liability
If your truck hurts someone or wrecks their property, this is the coverage that answers for it. Filings and most contracts look at this piece before anything else. We set the limit to what your jobs actually ask for.
Physical damage on the truck
Covers your own truck and dump body for collision, fire, theft and similar losses. We set the stated value carefully so a payout reflects what the truck is really worth. If you finance, your lender will usually require it.
Radius and use class
We write down how far you run and what you haul. Getting this wrong can mean a denied claim later, so we ask plainly and record it plainly.
Filings for your DOT number
If your operation needs state or federal filings, we handle them with the carrier once the policy is bound. We tell you what was filed and where.
Certificates of insurance
General contractors and pits often want a certificate of insurance before your first load. We issue them and explain what the endorsement wording on them means for you.
Signs it is time to look at your coverage
- A contractor rejected your certificate
- If a job asked for limits or wording your policy does not have, you need a fix before the next bid. We can tell you what is missing.
- You put on another truck or hired a driver
- The carrier has to know about each unit and each person behind the wheel. If someone left off the policy is driving when a wreck happens, the claim can get ugly fast.
- Your hauling radius changed
- Picking up work farther out, say from Fairburn down to Newnan and beyond, can push you past the radius on your policy.
- Your renewal jumped and nobody explained why
- Premiums move for reasons. We walk through the ones on your renewal so you know what you are paying for.
- You run a personal policy on a work truck
- Personal auto policies usually exclude commercial hauling. If that is you, it is worth fixing now.
How it works with us
- 1
We talk it through
You reach us by phone or video, or stop by our office. We ask what you haul, how far, how many trucks and who drives.
- 2
We gather the paperwork
Have your DOT number, truck VINs, driver license info and any past loss runs ready. Missing pieces just slow things down.
- 3
We shop and explain
We are licensed for property and casualty insurance and compare options from carriers that write dump and construction trucks. Then we go over each quote line by line so you see what is covered and what is not.
- 4
We bind, file and send certificates
Once you pick a policy, we bind it, handle the filings and get certificates to the contractors who need them.
What moves your premium
Dump truck premiums swing more than most people expect. A few things drive most of it. We point out which ones you can change and which you cannot.
- Driver records and experience
- Clean records and years behind the wheel of a heavy truck help the most. New drivers or recent tickets raise the price.
- Truck value and age
- A newer truck with a high stated value costs more to cover for physical damage. Older paid-off trucks sometimes carry liability only.
- Radius and what you haul
- Short local runs usually rate better than long ones. Hauling asphalt, demolition debris or equipment can rate differently than sand or gravel.
- Loss history and time in business
- Past claims follow you for several years. A newer operation with no track record usually pays more until it builds one.
- Limits your contracts require
- Some jobs demand higher liability limits than the minimum. Higher limits mean a higher premium, so we only raise them when the work calls for it.
Dump truck insurance questions
- Do I need cargo coverage to haul dirt and gravel?
- Often not much, since a load of fill or stone is worth little. Some contracts or shippers still ask for it anyway. We check what your customers require before adding cost you do not need.
- I only haul inside Georgia. Do I still need a DOT number?
- In many cases yes, depending on truck weight and the kind of work. Carriers that stay in state can have their own filing rules. We sort out which ones apply to your operation before we quote.
- A general contractor wants their name added to my policy. What does that mean?
- It means your liability coverage also protects them for claims that come from your work on their job. Most carriers allow this through an endorsement, sometimes for a small added charge. We set it up and send the certificate so you can start hauling.
- Is a tri-axle rated differently than a tandem?
- Usually, yes. Heavier trucks carry bigger loads and can do more damage in a wreck, so carriers price them higher. The value of the truck also matters for physical damage.
- What if I lease my truck onto another company?
- Their policy may cover you while you run under their authority. You may still need physical damage and non-trucking liability for the hours you are off dispatch. We can read the lease with you and point out where the gaps are.
Get your dump truck coverage sorted out
Tell us about your trucks, your drivers and the jobs you run. We will lay out the options in plain English and get your quote by phone.